Orbital AI Data Centers: A Weak Signal with Potential to Transform AI Infrastructure and Industrial Strategy
The emergence of plans to deploy artificial intelligence (AI) data centers in orbit represents a non-obvious infrastructural inflection with potential to reshape capital allocation, regulatory paradigms, and industrial positioning over the next two decades.
While AI’s rapid evolution predominantly focuses on terrestrial advances—from cloud computing to edge devices—SpaceX’s ambition to build orbital AI data hubs signals a frontier shift in how computational capacity might be provisioned and governed. This paper identifies orbital AI data centers as a weak signal poised to disrupt traditional cloud infrastructure assumptions and cascade into new regulatory and competitive ecosystems.
Signal Identification
This development is classified as a weak signal because, despite its technical feasibility and corporate backing, it remains under-discussed outside specialized aerospace and advanced-technology circles. It qualifies as a medium-plausibility, 10–20 years horizon innovation with exposure across technology infrastructure, regulatory policy, space industrialization, and capital markets.
Orbital AI data centers could catalyze a paradigm shift in AI infrastructure deployment, altering the geography of digital services, global data governance regimes, investment flows in space technology, and industrial supply chains.
What Is Changing
SpaceX’s stated effort to utilize its Starship vehicle’s unprecedented cargo capacity to both expand the Starlink satellite Internet constellation and construct an orbital AI data center (Scientific American 08/05/2024) introduces a novel modality of AI infrastructure: moving compute resources off-planet.
This initiative signals an evolution from conventional cloud and edge models, where AI workloads cluster in terrestrial data centers reliant on regional power grids and network infrastructures. It also challenges the existing dominance of North American-based cloud ecosystems, noted for advanced data governance and semantic knowledge graph technologies (Persistence Market Research 14/02/2024).
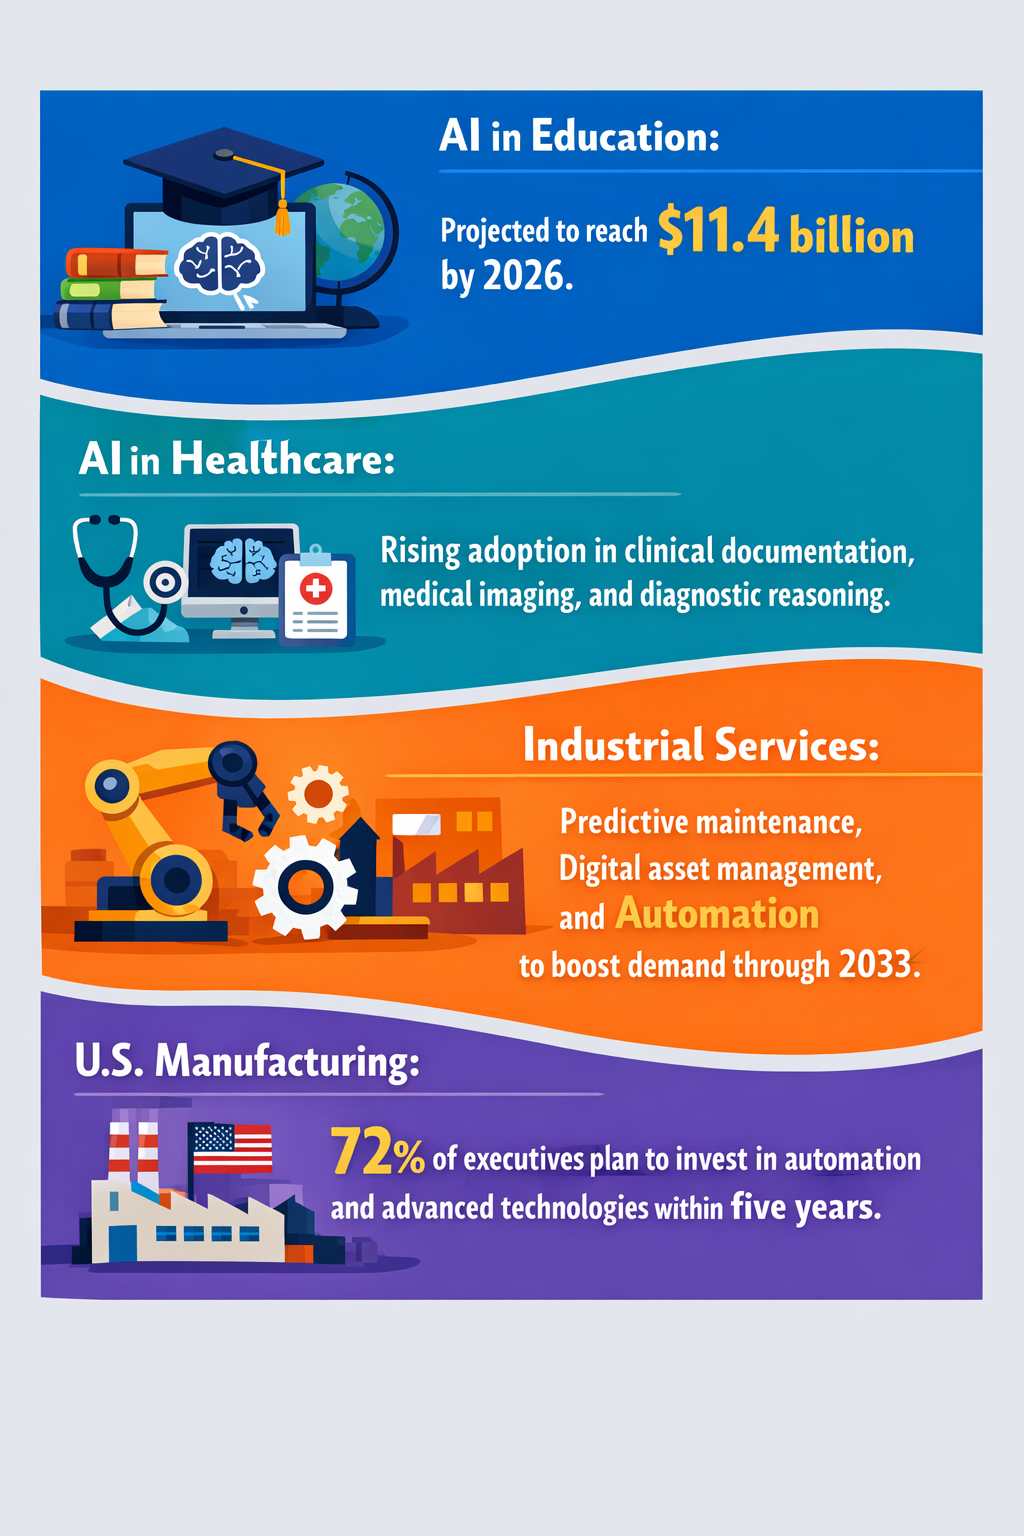
Concurrent trends in industrial automation and predictive maintenance strategies across manufacturing sectors (RoboHub 11/04/2024; Persistence Market Research 22/03/2024) are highly reliant on high-reliability, low-latency AI analytics. The spatial redistribution of compute assets into orbit could address terrestrial constraints such as energy scarcity, physical security, and regulatory fragmentation.
Moreover, permissive innovation environments are identified as critical for unleashing novel AI breakthroughs (Straits Times 30/01/2024). Orbital deployments may constitute a new innovation sandbox by circumventing earthbound regulatory velocity, permitting experimentation at aerospace-industry pace.
Disruption Pathway
The establishment of orbital AI data centers could accelerate as launch cost reductions from reusable heavy-lift vehicles (e.g., Starship) become entrenched, reducing economic barriers for space-based infrastructure. Enhanced satellite constellations, like Starlink, would enable ultra-high bandwidth, low-latency connectivity between Earth and orbital compute nodes, solving historic bottlenecks of space-based communication.
Traditional cloud models reliant on terrestrial data centers may face stress as differential energy costs, security risks, and geopolitical regulatory restrictions push data sovereignty concerns into orbit—introducing a new commons governance challenge. Jurisdictional ambiguity over orbital infrastructure and data could compel multinational regulatory regimes to evolve or fracture.
This may prompt structural adaptations such as the emergence of “space data zones” with bespoke regulatory frameworks, new liability regimes for orbital hardware failures, and competitive realignments involving aerospace manufacturers, telecommunications operators, and AI service providers.
Feedback loops could ensue if successful orbital AI centers attract specialized startups and public listings, raising new streams of venture capital focused on space-based IT ecosystems and altering capital markets’ sector weightings (Straits Times 30/01/2024). Existing dominant players may be forced to establish their own space infrastructure or form strategic partnerships, accelerating consolidation or fragmentation in cloud-industrial sectors.
Governance models may shift from national regulatory regimes to international consortiums or private-public hybrids managing space infrastructure and AI workloads at orbital altitudes. The ambiguous property and data rights in space will pose new legal and ethical dilemmas potentially surpassing terrestrial precedents in complexity.
Why This Matters
For capital allocators, this signal indicates a potential redirection of large-scale infrastructure investment from Earth-bound data centers to space technology sectors, entailing new risk profiles involving aerospace engineering, launch logistics, and cross-sector partnerships.
Regulators may need to formulate pioneering frameworks encompassing data sovereignty, cybersecurity, and liability across domains—combining space law with digital governance. The industrial structure could bifurcate, privileging actors with aerospace capabilities and forcing incumbent cloud providers to recalibrate strategies or cede niches.
Supply chains for AI hardware, satellite components, and launch vehicles might grow in strategic importance, prompting shifts in trade policy and national security assessments. Liability exposure will extend beyond traditional cyber risk to include orbital debris, hardware failures, and inadvertent interference with critical infrastructure.
Governments and industry will face complex decisions regarding technology ownership, dual-use control, and international collaboration—potentially reshaping long-term competitiveness and geopolitical positioning in AI and space-industrial domains.
Implications
Orbital AI data centers may catalyze a structural transformation of AI infrastructure supply chains, producing novel ecosystems of innovation and governance extricated from many terrestrial constraints. This is unlikely to represent a transient hype cycle or incremental upgrade but rather an emergent infrastructure vector that could redefine the locus of AI capability development.
This development should not be conflated with incremental scaling of terrestrial data centers or edge AI devices; its distinctive characteristic is the relocation of compute capacity to orbit, enabling new forms of connectivity, energy use, and regulatory interaction.
Competing interpretations might argue that the immense technical, economic, and regulatory challenges could stall orbital AI centers indefinitely, confining these to niche R&D efforts without scaling. Alternatively, skeptics may view orbital AI as an extravagant distraction from the immediate bottlenecks in terrestrial infrastructure and AI algorithmic breakthroughs.
However, considering the increasing integration of satellite internet with AI-driven industrial automation and semantic computing advances, the trajectory implies a plausible, albeit challenging, escalation into systemic change.
Early Indicators to Monitor
- Capital raises and M&A activity in space-based data infrastructure companies
- Patent filings on space-qualified AI hardware, cooling systems, and radiation-hardened processors
- Regulatory consultations or treaty negotiations addressing data governance in orbit
- Procurement announcements by major AI cloud providers regarding orbital deployment partnerships
- Launch frequency and payload manifest changes indicating increased AI or data center components
Disconfirming Signals
- Significant launch failures or catastrophic orbital hardware malfunctions raising safety concerns
- New terrestrial energy breakthroughs reducing the cost advantage of off-planet infrastructure
- International regulatory prohibitions on deploying commercial AI data centers in orbit
- Persistent latency or communication bottlenecks inhibiting integration with Earth-based users
- Investor pullback and capital reallocation from space-tech sectors into terrestrial AI resilience
Strategic Questions
- How should governments preemptively shape governance frameworks to accommodate orbital AI infrastructure while balancing innovation and sovereignty risks?
- What industrial partnerships and capital investment models will best position incumbents and challengers to leverage or defend against orbital AI data center developments?
Keywords
Orbital AI; Space-Based Infrastructure; Cloud Computing; Space Regulation; AI Data Centers; Industrial Automation; Capital Allocation
Bibliography
- Eventually, SpaceX hopes to use Starship's high cargo capacity to rapidly build out its satellite Internet constellation, Starlink, and to construct an orbital artificial intelligence data center. Scientific American. Published 08/05/2024.
- Growing adoption of predictive maintenance, digital asset management, and industrial automation solutions is expected to accelerate regional industrial services demand through 2033. Persistence Market Research. Published 22/03/2024.
- Leading Region: North America is expected to be the leading region, accounting for 35% in 2026, driven by strong AI adoption, advanced data governance standards, and major tech players driving cloud-based semantic graph solutions. Persistence Market Research. Published 14/02/2024.
- The vast sums flowing into artificial intelligence will produce a new generation of businesses and public listings, with the biggest breakthroughs likely to emerge in places where people are allowed to experiment, fail and try again. Straits Times. Published 30/01/2024.
- In a recent survey of U.S.-based manufacturing executives at companies with sales of least $1 billion, 72% of respondents said that their companies will invest in additional automation or other advanced-manufacturing technologies in the next five years. RoboHub. Published 11/04/2024.